Roofing financing in Branson, MO turns a $12,000 to $20,000 surprise into a monthly payment you can actually plan around. Between hail rolling off Table Rock Lake and shingles baking through Ozark summers, most homeowners here face a roof decision before they've saved for one. This guide breaks down every real financing path, what lenders actually check, and where insurance or assistance programs can cut the bill before you borrow a dime.
Your Roofing Financing Options in Branson, MO
Four paths cover almost every situation: home equity borrowing, personal loans, contractor payment plans, and FHA-backed improvement loans. Each one trades speed, cost, and collateral differently, so the right fit depends on your timeline and how much equity you've built.
Home Equity Loans and HELOCs
A home equity loan hands you a lump sum repaid at a fixed rate. A home equity line of credit, or HELOC, is a line of credit, like a credit card, except you are borrowing against the equity of your home. Both options typically carry lower rates than unsecured products, which matters on a full roof replacement.
The trade-off is risk and time. You should only consider a HELOC if you're confident you can keep up with the loan payments, because if you fall behind or can't repay the loan on schedule, you could lose your home. Approval also tends to run two to four weeks because of appraisal and title work.
Personal Loans for Roof Repairs
Often marketed as home improvement loans, personal loans are unsecured, so your house isn't collateral if payments slip. Approval is usually faster, sometimes within a day or two, which helps when a leak won't wait on paperwork. The catch: average rates run higher than equity products, and terms vary a lot from lender to lender, so compare at least two offers before signing.
Contractor Financing Programs
Many roofing companies partner with third-party lenders to offer payment plans at the time of your estimate. These often include promotional windows like same-as-cash periods or a flat low monthly payment for approved credit. Terms shift often between lenders, so confirm the current rate and fees with your contractor rather than assuming an advertised number still applies.
In our own estimates around Branson, this is usually the fastest path to a signed contract. Request a free estimate and we'll walk you through current lending partners alongside the project price, so you're comparing real numbers instead of a sales flyer.
FHA Title I Loans: The Option Most Branson Homeowners Never Hear About
This is the financing path local roofing sites rarely mention, and it's worth knowing about if you have little home equity. HUD insures private lenders against loss on property improvement loans they make, and improvements must substantially protect or improve the basic livability or utility of the property. A Title I loan isn't a government handout; it's a regular loan from a private lender, with HUD backing the lender instead of your equity.
Because the loan isn't tied to your home's appraised value, it can work for homeowners who are underwater on equity or who bought recently. You'll still go through a private, Title I-approved lender, and loans above $7,500 require a lien on the property.
How Roof Financing Works, Start to Finish
Roof financing is a loan that lets you pay for the work now and repay it in monthly installments. Banks, credit unions, and third-party lenders provide these loans, sometimes arranged directly through the contractor, with fixed payments based on your approved terms.
The process is usually three steps:
- A free in-home estimate and inspection.
- A conversation about which lending partners fit your credit profile and project size.
- A short online application, often with same-day pre-approval.
Before signing anything, ask the lender these questions:
- Is the rate fixed or variable for the entire term?
- Are there fees for paying it off early?
- What happens if a payment is late?
- What's the exact monthly payment, loan length, and total cost over the full term?
Get the answers in writing, not just verbally from a sales rep.
Here's how the common options stack up in 2026:
| Financing Type | Typical APR Range | Credit Score Threshold | Approval Speed | Collateral Required |
|---|---|---|---|---|
| HELOC | ~7%-10% | 620-680+ | 2-4 weeks | Yes (home) |
| Personal Loan | ~9%-18% | 600-660+ | 1-3 days | No |
| Contractor Financing | 0%-15% (promo periods vary) | Varies by lender partner | Same day to a few days | No |
| FHA Title I Loan | ~8%-12% | More flexible than conventional | 1-2 weeks | Only on loans over $7,500 |
Rates and thresholds shift with market conditions, so treat these as planning ranges, not guarantees. For plain-language breakdowns of APR, fixed-versus-variable terms, and loan disclosures, the Consumer Financial Protection Bureau's HELOC guide is worth ten minutes before you sign anything.
First Step Before Financing: What Insurance Usually Covers
Find out what your policy already pays for before you borrow for anything. Hail or wind damage is often insurance-eligible if it's documented and falls within your policy terms. Slow, age-related wear typically isn't covered and becomes an out-of-pocket or financed expense instead.
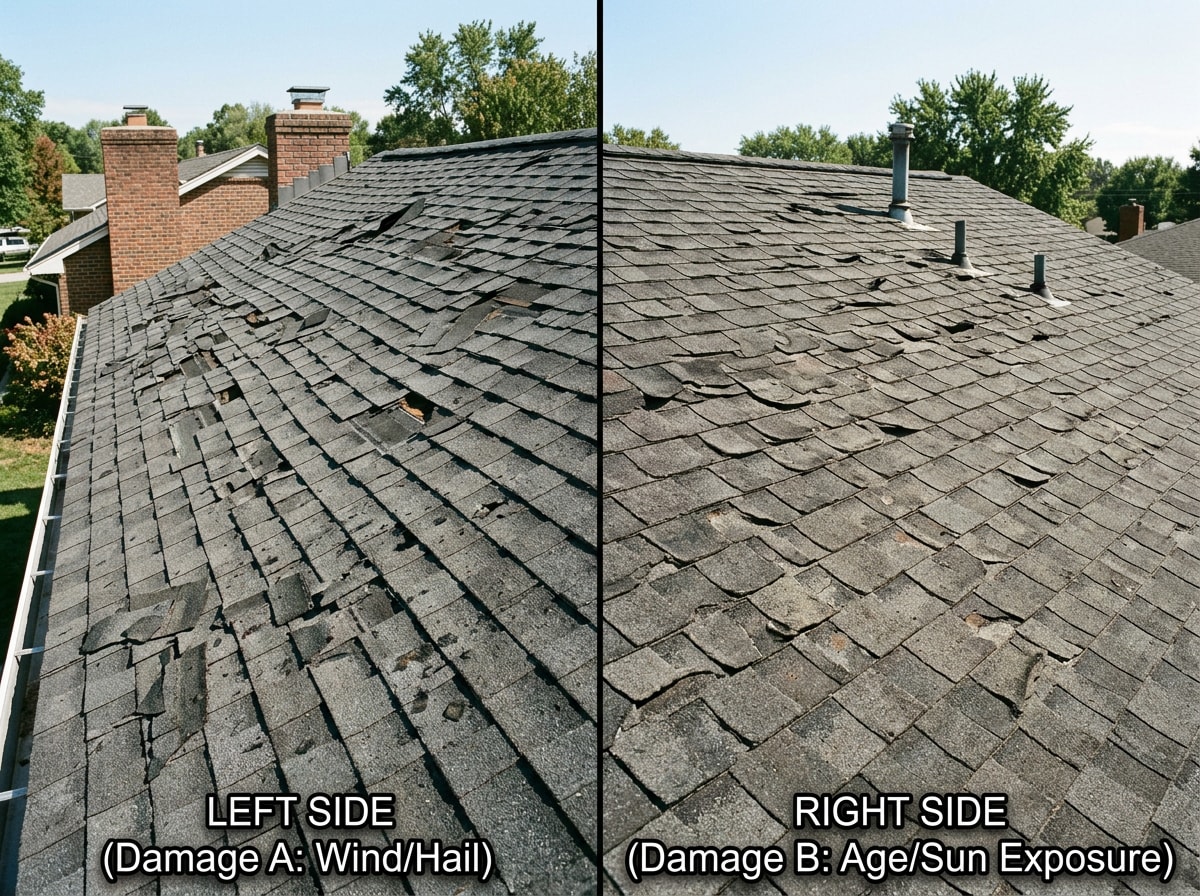
Most Missouri consumers know that homeowners insurance covers the house they live in, plus most of your possessions, and it covers your additional cost of living if your home becomes uninhabitable due to an unforeseen event. What it doesn't cover is just as important to understand before you assume financing is your only option.
If a storm is involved, document the damage with clear photos or video, contact your insurer promptly, and work with a contractor who can walk the roof with your adjuster. Our crews handle this constantly after Taney County storm systems; a roof inspection before you file anything gives you photo documentation an adjuster can't argue with. If the damage is from wind or hail, our storm damage roof repair team can coordinate directly with your insurance company. For state-specific guidance on what a homeowner policy must cover, the Missouri Department of Commerce and Insurance publishes consumer resources on deductibles and covered perils.
Help for Lower-Income Households: Weatherization and Assistance Programs
Homeowners who don't qualify for standard loans, or whose insurance won't cover the full cost, aren't necessarily out of options. Households at or below 200% of the poverty income guidelines, or that receive Supplemental Security Income, are considered under DOE guidelines as eligible for weatherization services. Taney County residents can qualify depending on household income and need, and roof repairs tied to energy efficiency sometimes fall within scope.
These programs vary by funding cycle and local administering agency, so eligibility and available services should be confirmed directly. The Department of Energy's page on applying for weatherization assistance explains income limits and how the application process works.
Why This Matters More in Branson Than Other Markets
Branson's roofing demand spikes hard after hailstorms, and financing offers tend to be marketed loosely during that window, same-as-cash promos, "0% for 12 months" banners, and flexible terms that change by the week. We've seen homeowners sign a contractor financing agreement during a storm rush without confirming the post-promo rate, only to find a much higher APR kicks in after month 12. Ask for the full amortization schedule before you sign, not just the promotional headline rate.
If your home is near Branson, MO and you're comparing financing against a full tear-off versus a repair, start with a written scope from a roofing contractor you can verify locally, not just a national lending app. A roof replacement quote should break out material, labor, and disposal costs separately so you know exactly what you're financing.
FAQ
Can I Finance My Roof Replacement?
Yes. Most homeowners finance a roof replacement through a contractor payment plan, a personal loan, or a home equity loan or line of credit. Contractor financing is usually the fastest path since it's arranged at the time of your estimate, while HELOCs tend to offer lower rates for those with built-up home equity.
What Credit Score Do I Need to Finance a New Roof?
There's no single universal number. It depends on the lender and the financing type. Contractor-arranged financing programs tend to be more flexible with credit requirements than a traditional personal loan or HELOC, so it's worth asking even with a lower score.
Does Homeowners Insurance Cover Roof Replacement?
It depends on the cause of damage. Storm and wind damage is often covered if documented properly, while gradual wear typically isn't and becomes an out-of-pocket or financed expense. See the insurance section above, or visit the roof replacement page for a full breakdown of what's usually included.
Can I Finance a Roof With Bad Credit?
Bad credit usually affects your rate and terms rather than ruling out financing entirely. Contractor-backed programs and FHA Title I loans tend to be more accessible for borrowers with lower scores. Request a free estimate to discuss which financing path fits your situation.
How Much Does a New Roof Cost in Branson, MO?
Cost depends on roof size, pitch, material, and whether decking repairs are needed. Most Branson homeowners budget somewhere between $8,000 and $20,000 for a full asphalt shingle replacement, with metal roofing running higher. A written, itemized estimate is the only reliable way to know your actual number.
Does Rick's Roofing Offer In-House Financing?
We work with lending partners to offer flexible payment plans at the time of your estimate, including promotional same-as-cash periods for approved credit. Visit our homepage or contact us directly to see current offers for your project.
---
About the author: This guide was reviewed by the team at Rick's Roofing, a licensed and insured roofing contractor serving Branson, Springfield, Nixa, Ozark, and the greater Ozarks region. Our crews handle insurance-related storm claims and financing conversations on roofs every week, which is why we built this guide around the questions homeowners actually ask at the estimate table, not just the ones that make for a good ad. Questions about your specific project? Reach out here.